Who Is on the Hook? How LacunaIndex Counts Leadership Disclosure Instead of Judging Executives
Diligence analysts want to know whether accountability at an issuer runs deeper than the chief executive and chief financial officer, but impressions of "management quality" are unfalsifiable; this post shows how LacunaIndex replaces them with countable disclosure signals.
Every diligence memo eventually reaches the management paragraph. It usually reads like a character reference: "experienced team," "strong operator," "thin bench." These phrases are easy to write and impossible to check. Two analysts can read the same earnings call and walk away with opposite impressions, and nobody can point to the evidence behind either one.
LacunaIndex handles leadership differently. It does not try to assess whether an executive is good. It asks a narrower question that a reader can verify: does the issuer publicly disclose an accountability structure that holds up under scrutiny? The rest of this post explains how that question is turned into counts, and what an analyst can do with the output.
The rule that governs everything: no anchor, no claim
The leadership synthesis step is written around what the system calls the anchor rule. Every observation, dimension summary and "what is missing" item must be tied to one of three things:
- A specific public disclosure, such as an earnings call transcript, an annual report (Form 10-K), a quarterly report (Form 10-Q), a current report (Form 8-K), a proxy statement, an investor day presentation, a press release or the investor relations website.
- A countable disclosure signal, such as the number of named speakers on earnings calls or the number of reporting segments with a named leader.
- A measurable absence of disclosure, in a place where peers routinely disclose.
If a statement cannot be tied to one of those, it does not appear. The instructions to the language model that drafts this section explicitly rule out personality assessment, capability inference, commentary on how long someone has been in the role, succession speculation, and visibility scores for individual named executives. A banned-word list backs this up: terms such as "weak," "visionary," "charismatic" and "thin bench" are stripped from the output before a reader sees it.
For an analyst, the practical effect is that the section reads as a list of facts you can go and check, not a verdict you have to take on trust.
Four dimensions, each built from counts
The framework scores the leadership layer along four dimensions. Each one is described in terms of what can be counted:
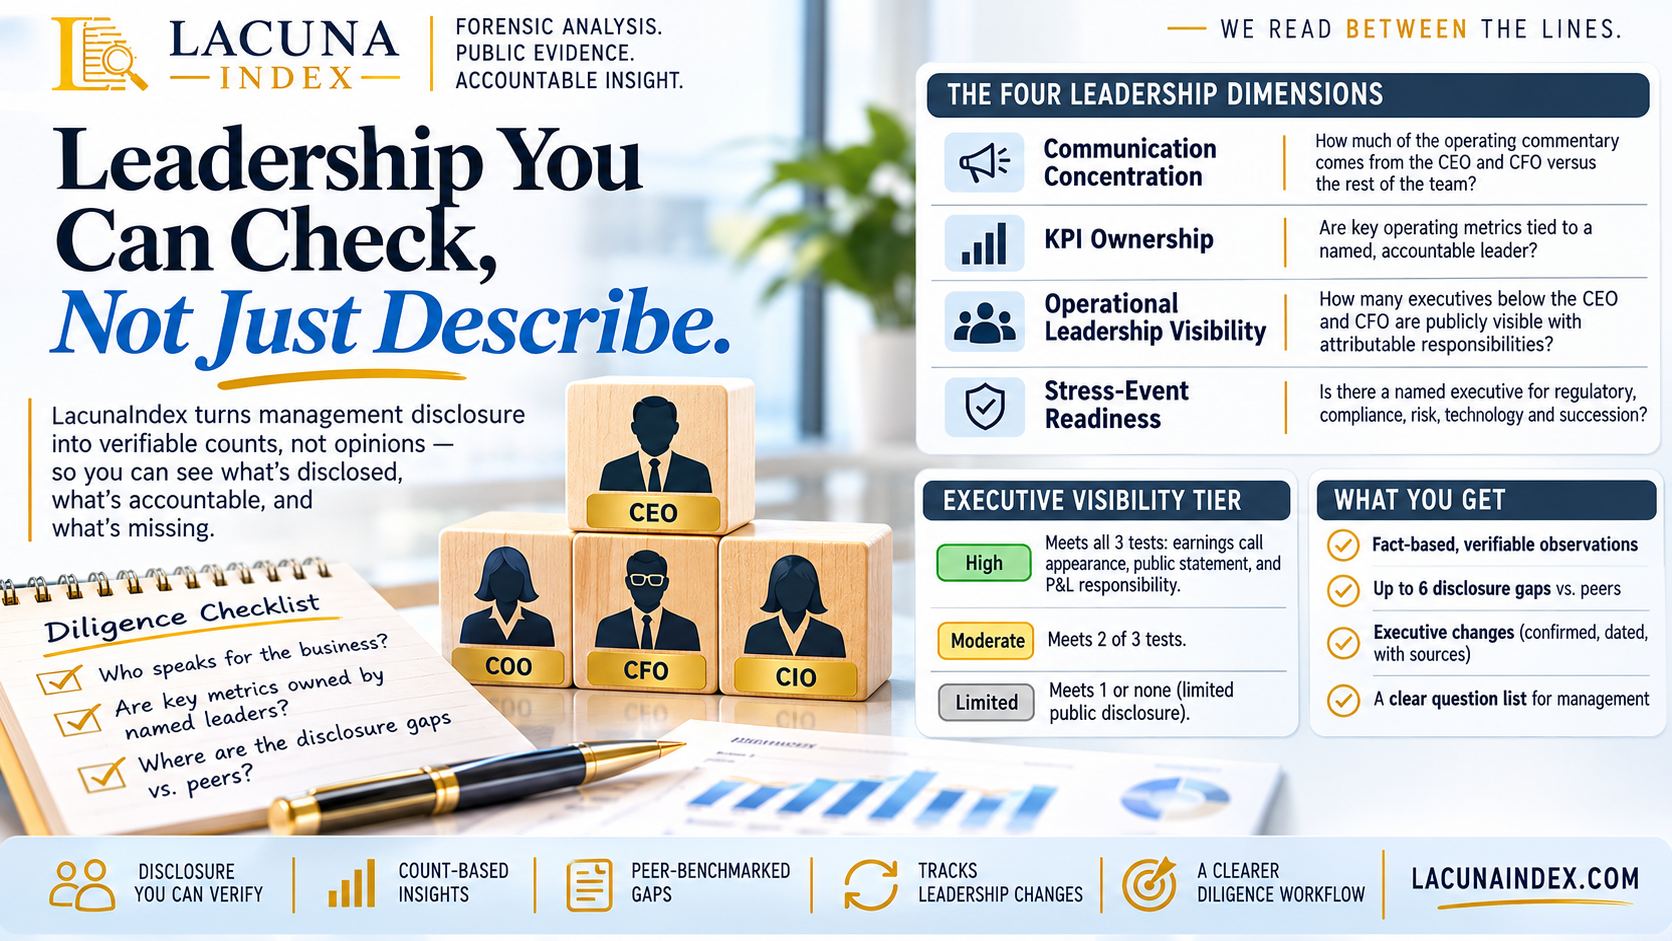
1. Communication concentration. How much of the public operating commentary comes from the chief executive and chief financial officer versus the rest of the team? The anchors include the chief executive's share of executive speaking on the last four earnings calls, how many named operating executives gave prepared remarks, and how many answered analyst questions.
2. Key performance indicator ownership. Are the operating metrics an issuer reports attributed to a named, accountable person? The anchors include how many reporting segments have a publicly named leader, how many of those leaders appeared on an earnings call in the last four quarters, and how many named strategic initiatives have a named owner versus none.
3. Operational leadership visibility. How many executives below the chief executive and chief financial officer are publicly visible? The anchors count those with at least one earnings call appearance, at least one attributable public statement in the last twelve months, and publicly attributed profit-and-loss responsibility for a reporting segment.
4. Stress-event disclosure readiness. If a regulatory, operational, strategic or succession event hit, is there a named person who could credibly speak to it? The anchors cover whether a named executive owns regulatory, compliance and risk, whether that person has appeared in a public forum recently, and whether a named technology officer exists. For succession, the system counts only disclosure: how many segment leaders have publicly named potential successors, and how many of those successors have disclosed segment profit-and-loss ownership, board exposure, or a dated investor day or earnings call appearance. It never scores perceived capability.
Each dimension comes back as one sentence stating the count-based observation, plus one to four short anchor strings, for example a transcript name with "three operating speakers other than the chief executive," or a proxy page reference noting that no segment leader is named for a given business.
The "what is missing" list is benchmarked against peers
The same step produces up to six "what is missing" items. Each one has to cite a peer disclosure standard, such as "a named segment president appears on quarterly earnings calls, which is standard across N of M cohort peers." That requirement matters. An absence only counts as a gap when comparable issuers do disclose the item. Silence on something nobody discloses is not a finding.
Where the count is fully mechanical: the visibility tier
One part of this works with no language model at all. The per-executive visibility table is built by a deterministic transform. It takes the executive roster the system has already assembled and fills in five columns drawn from public disclosure: accountability, ownership, key performance indicator attribution, continuity and public execution responsibility. Empty cells mean the issuer has not publicly disclosed that signal, and the table says so rather than guessing.
Each executive then receives a visibility tier from three yes-or-no tests:
- Appeared on an earnings call in the last four quarters.
- Has at least one attributable public statement in the last twelve months, such as a named press release quote, a conference appearance or a named interview.
- Has publicly attributed profit-and-loss responsibility for a reporting segment.
Meeting all three tests gives High, two gives Moderate, and one or none gives Limited. There is no editorial adjustment. Two people reading the same inputs get the same tier every time.
The table also carries a short "communication structure" summary made of counts: the chief executive's share of executive voice (as a rounded percentage where available), the number of named operating speakers, the number of executives with segment financials, and how many chief financial officer roles carry key performance indicator attribution.
Why a Limited tier is not an accusation
The wording around the tier matters for how an analyst should use it. A Limited tier says the issuer has disclosed little about that person in public. It does not say the person is ineffective. The useful question is comparative and practical: when a segment generates a large share of revenue and its leader is Limited, who do you call, and where will you find that leader's commitments on the record? That is a diligence request list, not a character judgment.
Leadership change tracking uses the same discipline
LacunaIndex also surfaces executive changes for a company or a cohort, with rules that avoid common noise:
- Confirmed events only. The panel shows confirmed changes, and it hides itself when there are none in the window, so a quiet page stays quiet.
- Announcement date, not discovery date. The lookback window, 90 days by default, is applied to when the change actually took effect or was announced. A departure the system happens to re-discover today does not appear as news.
- Duplicates collapsed. The same person, same change type, same company counts once, keeping the most recent and highest-confidence record.
- Sources per row. Each entry shows where it came from, so you can check it.
A practical way to use this in diligence
- Start from the counts, not the narrative. If the chief executive's share of executive speaking is very high and few operating executives speak, note that as a fact about the disclosure structure.
- Check segment ownership against revenue. Look for large reporting segments with no named leader, or with a leader who has not appeared publicly in four quarters.
- Turn gaps into requests. Each "what is missing" item, with its peer benchmark, converts directly into a management question or a data room request.
- Look at recent changes alongside the tiers. A recent departure in a role the table marks as the sole named owner of a segment is a different matter from one in a role with several named peers.
What this approach does not do
It does not rate management quality, predict departures, or tell you who should succeed whom. It is deliberately limited to what the issuer has put on the record and what can be counted. We think that is the right boundary for a diligence tool: the output can be disputed line by line, and every line points back to a document.
LacunaIndex does not provide investment advice. Outputs are intended to structure diligence questions and are not a substitute for independent analysis.